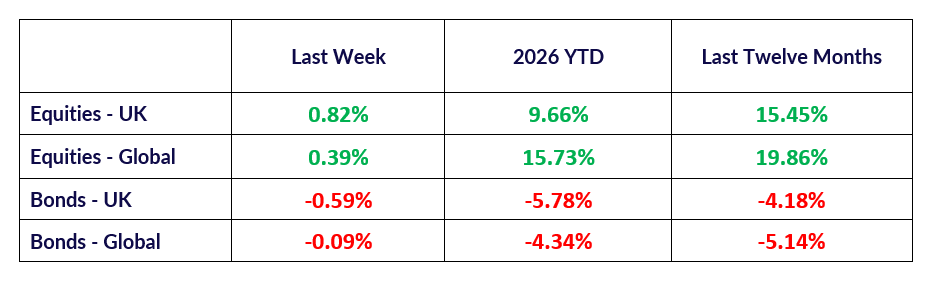
The infoshot to help kick-start your week
Coming up this week:
Big banks reporting for Q3 – Tuesday & Wednesday
Several big US banks, including JP Morgan, Bank of America, Morgan Stanley and Citigroup, are set to release their Q3 earnings. With trading volumes smashing records in Q2, most of the banks heralded the health of the US economy. Three months on, inflation remains stubborn, interest rates have been risen, and US national debt has surpassed the $40tn mark. Analysts will be keeping a keen eye on whether the banks’ optimism has changed, particularly now the US financial sector has fallen more than any other sector in the past month declining around 4%.
Last week:
US markets reach record high as IMF warns about threats to global growth
On Tuesday, the US’s leading index achieved a record high despite the sell-off in bonds. Markets rallied in response to high earning expectations thanks to the trillions of dollars pouring into AI infrastructure. According to Factset, analysts are expecting Q3 earnings growth of 29.5%. Chipmakers Nvidia and Micron are expected to account for more than a third of that growth. Some of this bullishness was dented on Thursday after OpenAI told investors that revenue for this year will be $50bn, $20bn less than estimated in September.
With AI development and the race for superintelligence showing no signs of slowing down, OpenAI CEO, Sam Altman advocated for a light touch regulatory stance in an interview on Monday. He said that the world should just accept “some bad things happening” in exchange for the benefits AI may bring. Later in the week, Axios reported that top executives at OpenAI and Anthropic have been privately preparing for a “day after event” within the next six to twelve months that causes a major public and political revolt against AI.
Speaking in Singapore, International Monetary Fund (IMF) Managing Director, Kristalina Georgieva warned that the AI investment boom, high energy prices and record levels of public debt are threatening global growth. Georgieva said spending on AI as a proportion of GDP will surpass the buildouts for railroads, power grids and telecoms combined, but will widen global inequality due to the limited geographical scope of the AI supply chain. She also warned that IMF research estimates that 40% of jobs will be augmented or eliminated by AI, with this rising to 60% in advanced economies.
Trump teams up with Putin to try to drive down diesel prices
Oil prices were volatile again last week after tankers were attacked in Hormuz and signs that the US military is considering more strikes on Iran. Prices came down a little after Trump said he won’t attack Iran before the midterm elections in November.
After convincing other G7 nations to release 100mn barrels of stockpiled oil the previous week, Trump struck a deal with Vladimir Putin to immediately release 300,000 tonnes of Russian diesel into the “American and global marketplace”. A further 1.5mn tonnes are set to be released from November. With his poll numbers still through the floor, Trump will be hoping the diplomatic backlash is worth it, and the Russian oil can drive down domestic prices before the midterms. However, the first 300,000 tonnes literally just covers around half a day of US diesel consumption, so its potential price impact looks questionable.
Notice:
For regulated financial advisers and investment professionals only, Copia does not provide financial advice, and the contents of this document should not be taken as such.
The performance of each asset class is represented by certain Exchange Traded Funds available to UK investors and expressed in GBP terms selected by Copia Capital Management to represent that asset class, as reported at previous Thursday 4:30pm UK close. Reference to a particular asset class does not represent a recommendation to seek exposure to that asset class. This information is included for comparison purposes for the period stated but is not an indicator of potential maximum loss for other periods or in the future.