The infoshot to help kick-start your week
Coming up this week:
US midterms – Tuesday
The final polls suggest Democrats will have enough to comfortably flip control of Congress following Tuesday’s US midterm elections. They also have a narrow lead in many key Senate races. Trump has simply bypassed most checks and balances through executive orders over the last two years, but losing both houses will open a wave of subpoenas and investigative committees, potentially drowning Trump’s next two years in office in litigation and impeachment trials. It may also have repercussions for the AI boom by making it possible for Democrats to pass bills which limit data centre buildouts and impose new regulations on the frontier labs.
The expectation has been for the US and Israelis to increase their attacks on Iran once the midterms are done. The US sent 10,000 more sailors and marines to the Middle East in October and on Friday, Democratic Senator Chris Murphy said he was briefed on the post-midterms war plan, calling it “insane” before adding “it will lead to a devastating escalation and the likely destruction of our commitment to the rule of law.” However, oil prices have fallen today after Axios reported that Trump told Netanyahu he would like to give diplomatic talks more time after the midterms.
Bank of England interest rate decision – Thursday
The Bank of England’s Monetary Policy Committee meets this week to make their latest decision on UK interest rates. Unlike the Federal Reserve and the Bank of Japan, who both elected to hold interest rates last week, the Bank is widely expected to raise the base rate from 3.75% to 4%. Inflation rose to 3.5% in September, and nothing suggests it may slow down anytime soon so many analysts are expecting this to be the first of four quarter-point rises over the next 12 months.
Last week:
Tech down for third week in a row
Tech stocks fell for the third week in a row as investors reacted to more news around AI spending. Alphabet shares plummeted 12% on Thursday, wiping $500bn off their market value, after they reported negative cash flow for the second quarter in a row and that they plan to spend another $205bn this year on AI investments. They also revealed that AI summaries are really starting to hurt Google’s advertising revenue. Reddit shares also fell after they reported huge declines in web traffic caused by AI. Amazon shares fell after they reported negative cash flow of $42bn and a six-fold spending increase in the last quarter. In contrast, Microsoft suffered a minor fall after reporting they spent $5bn less on AI investments. Earlier in the week, Microsoft announced they would offer buyouts to 60,000 employees, more than a quarter of their global workforce, as AI’s impact on employment continues to become more apparent.
Anthropic’s long-awaited S1, the registration statement US companies must file before they can go public, was filed on Monday. There was a staggering 94 pages of risk factors, including warnings on how the existential risk posed by their technology could impact their brand, insurance coverage and revenues. The numbers enclosed showed a net loss of $80bn for the first six months of the year, and infrastructure agreements that will cost $657bn over the next few years. Revenue increased 14-fold to $16.3bn, however that only covers January to June and precedes the end of “token maxing” by many large tech firms. There was more bad news for the AI boom on Friday when Blackstone warned Anthropic that they may get a junk rating after the IPO forcing them to pay higher yields on their debt.
Tame Autumn Budget pleases markets
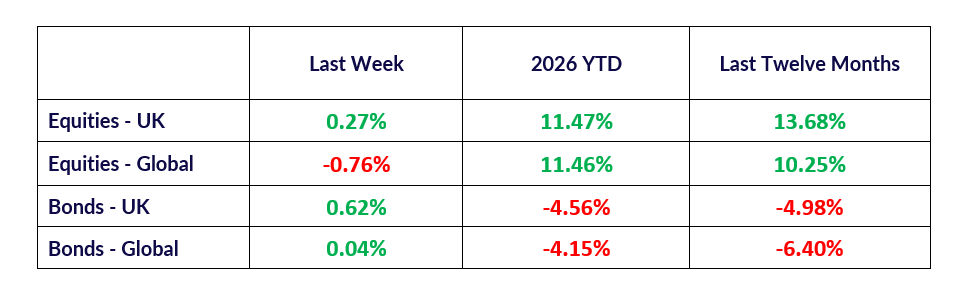
The continued rotation away from US tech, plus the rather tame Autumn Budget and some strong corporate earnings led to some small gains for our home market last week.
Andy Burnham said afterwards that he’d have liked a more “radical budget”. The lack of radicalism even helped the share price of slot machine makers like Evoke and Rank Group who were expecting a tax hike on takings far higher than the 5% one they received. Major UK banks didn’t rally but would have been relieved when the profit surcharge was raised less than expected to just 6%.
In a week full of big oil reports, BP and Shell inevitably joined their US counterparts in reporting huge profits for Q3.
Notice:
For regulated financial advisers and investment professionals only, Copia does not provide financial advice, and the contents of this document should not be taken as such.
The performance of each asset class is represented by certain Exchange Traded Funds available to UK investors and expressed in GBP terms selected by Copia Capital Management to represent that asset class, as reported at previous Thursday 4:30pm UK close. Reference to a particular asset class does not represent a recommendation to seek exposure to that asset class. This information is included for comparison purposes for the period stated but is not an indicator of potential maximum loss for other periods or in the future.