The infoshot to help kick-start your week
Coming up this week:
Autumn Budget – Wednesday
With total UK government debt now estimated to be above £3tn for the first time, John Healey will be looking for ways to balance the books when he delivers his first Autumn Budget as Chancellor. On Tuesday, he ruled out raising Capital Gains Tax (CGT) and Prime Minister Andy Burnham has previously indicated there will be no increase to the main rates of income tax, NI or VAT. Instead, UK bank profits look a likely target to help meet fiscal goals. Raising the corporation tax banks pay from 3% to 5.5% could raise £1bn to £2bn a year, and a similar raise on the profits generated by gambling machines could add up to another £460mn.
Energy & tech reporting – Tuesday to Friday
BP, Shell and Chevron are all expected to post huge jumps in profits as the conflict in Iran continues to push oil prices to record highs. Investors will be looking out for signs that they might start increasing spending plans or whether they’ll prioritise paying off debt and increasing share buyback programmes.
Three more Magnificent Seven firms, Alphabet, Amazon and Microsoft, report their Q3 numbers this week. Capital expenditure and the impact of AI spending on cash flows will once again come under heaving scrutiny as the US’s tech index tries to avoid falling for the third week in a row.
Last week:
Dip-buying not enough to turn the tide
Following the previous week’s AI sell off, investors started the week buying the dip on Monday. The positive momentum continued for a few days but was dashed on Thursday when the US’s leading tech index suffered its steepest single day decline since June. The sentiment shifted after Meta posted negative cash flow for the first time since 2012 and announced new non-voting shares to raise more capital for AI spending. Meta were also hit by their largest fine yet. A judge in New Mexico ordered the company to pay $25bn after they were found guilty of lying about how they handled user data.
Reports later Thursday morning suggested OpenAI have cut their latest valuation from $1.4tn to $1.25tn. OpenAI declined to comment on why they’ve lowered their fundraising target, but investor fatigue and the growing scepticism around the AI buildout may have played a role.
However, dwindling AI enthusiasm didn’t spread to HR departments last week, with Barclays bank announcing 5,000 job cuts as the company hands over more work and processes to AI. Barclays’ 5% cut in their global workforce is part of their ongoing modernisation plan. According to the bank, AI is simply the “icing on the cake” of the strategy. Nearly two thirds of the job losses target their support functions and developers.
Historic merger moves closer
Elon Musk announced that both SpaceX and Tesla have formed special committees to explore a potential merger. Based on current valuations, the merger would be the largest in history. If Musk can convince 50% of Tesla shareholders to vote for the merger, it would give him greater voting control at Tesla and open the door for deeper synergies between Tesla’s cars and robotics and SpaceX’s engineering capabilities and satellites.
UK inflation and jobs numbers boost rate hike chances
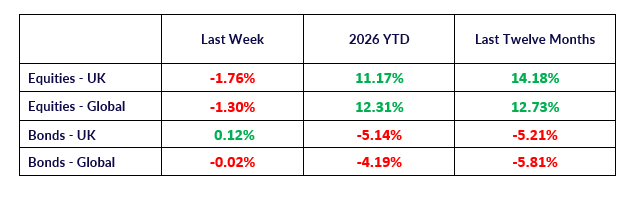
Our home market fell this week after higher-than-expected inflation data and another surge in the price of oil. The latest reading from the Office for National Statistics (ONS) showed inflation rose more than expected to 3.5%, primarily due to the rising cost of fuel. Unemployment fell more than expected to 4.7%, increasing the chances of a November rate hike by the Bank of England.
Last week’s oil prices will have done little to help challenges around inflation. Brent crude touched its highest price this year. It’s now up around 60% since the US and Israel launched their initial strikes on Iran at the end of February.
Israelis head to the voting booths tomorrow for the first time since Hamas’ attacks on 7 October 2023. Although polls indicate the current alliance between Prime Minister Benjamin Netanyahu and the ultra-orthodox parties lack a clear route to maintaining power, any significant policy change regarding the conflict in Iran or the situation in Gaza is likely to come down to how the Arab parties perform and what role they can play in a governing coalition.
Notice:
For regulated financial advisers and investment professionals only, Copia does not provide financial advice, and the contents of this document should not be taken as such.
The performance of each asset class is represented by certain Exchange Traded Funds available to UK investors and expressed in GBP terms selected by Copia Capital Management to represent that asset class, as reported at previous Thursday 4:30pm UK close. Reference to a particular asset class does not represent a recommendation to seek exposure to that asset class. This information is included for comparison purposes for the period stated but is not an indicator of potential maximum loss for other periods or in the future.