The infoshot to help kick-start your week
Coming up this week:
AI under the earnings spotlight – Tuesday & Wednesday
AI hyperscaler spending will come under scrutiny again on Wednesday when Meta release their latest quarterly results. Last week’s release of Muse Wonder and Muse Wonderful, which according to Mark Zuckerberg has taken Meta to the “AI frontier”, comes too soon to have an impact on profits, but investors will be looking for signs that Meta’s investment in datacentres and AI infrastructure is starting to generate returns.
Following an 11% fall during the tech sell off last week, SpaceX will release their latest quarterly earnings on Wednesday. Tesla also publish their Q3 report this week, and we could see some interesting commentary on a potential Elon Musk-led merger of the two firms.
Second round of Brazil’s election – Sunday
Latin America’s largest economy will go to the polls on Sunday. Flávio Bolsonaro, son of the imprisoned former President Jair Bolsonaro, defied expectations to win the first round two weeks ago and looks likely to secure power.
Bolsonaro Jr has promised cuts to spending and welfare, more oil drilling and investment in the critical minerals sector. His father, who will be pardoned by his son if he succeeds, significantly increased deforestation in the Amazon during his tenure, and a return to more lax environmental policies could have a worldwide knock-on effect that accelerates global warming. If Bolsonaro Jr wins, Trump will have secured another populist right-wing ally in Latin America, leaving Mexico and Uruguay as the largest remaining left-wing governments.
Last week:
AI sell off
A troubling week for AI shares saw the US’s tech index tumble nearly 4.5% when markets closed on Friday.
Rising US inflation numbers helped trigger the Wednesday-to-Friday sell off. The final inflation numbers before the US midterms from the Bureau of Labor Statistics showed inflation rose to 3.7% in September. The Producer Price Index (PPI) soared well above expectations to 6.3%, the largest increase since December 2022 and more than triple the Fed’s 2% target. Chances of a rate hike have increased on the back of the readings.
Problems in the neocloud sector (rentiers of GPU computing power and AI infrastructure) exacerbated the sell off at the centre of the AI trade. CoreWeave caused a panic when some of their bond yields reached 15% making it harder for the company to borrow more money to cover their spending plans. 11% owned by Nvidia, CoreWeave are very entangled in the circular funding between AI hyperscalers and have large compute contracts with Microsoft, Alphabet, Oracle and Meta. Another Nvidia backed neocloud, Firmus, recently withdrew their IPO listing after plans to build 1.6 gigawatts of AI data centre infrastructure were cancelled. This weekend Microsoft terminated their involvement in the project with Nscale to build the UK’s largest AI data centre in Loughton, Essex, due to power supply issues.
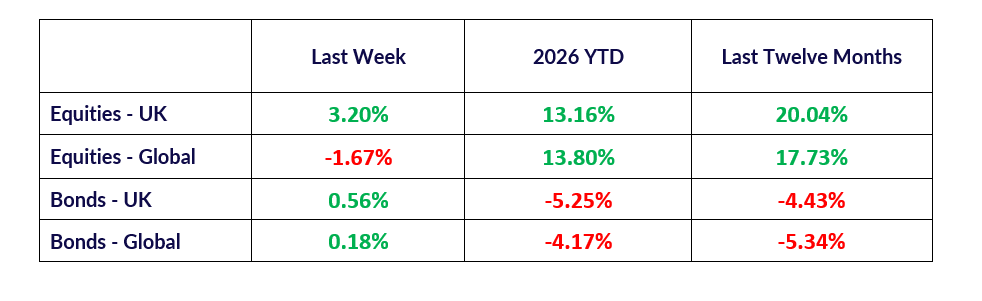
All the turmoil in the AI trade sent investors to more defensive assets and regions, with our home market benefiting and having its best week in six months.
More mixed results for US banks
We saw some more mixed results from the major US banks that reported last week. JP Morgan and Wells Fargo both missed revenue expectations, whereas Goldman Sachs and Citigroup beat expectations. All were relatively bullish in their comments on the AI boom, and despite the problems in the US economy, they remain optimistic about the health of US consumers and businesses.
Oil prices surge as Trump gets closer to Putin
A week on from Trump’s deal to import Russian diesel, oil prices surged 10% sending barrels of crude and brent over $101 and $110 respectively. On Friday, Trump blocked new sanctions on Russia two days before they were due to take effect. As Trump gets closer to Putin and the divisions between Trump and Zelensky grow, the SpaceX owned Starlink implemented a speed limit on their terminals hampering the effectiveness of Ukrainian drones and the ability to defend against incoming Russian ballistics.
Notice:
For regulated financial advisers and investment professionals only, Copia does not provide financial advice, and the contents of this document should not be taken as such.
The performance of each asset class is represented by certain Exchange Traded Funds available to UK investors and expressed in GBP terms selected by Copia Capital Management to represent that asset class, as reported at previous Thursday 4:30pm UK close. Reference to a particular asset class does not represent a recommendation to seek exposure to that asset class. This information is included for comparison purposes for the period stated but is not an indicator of potential maximum loss for other periods or in the future.