The infoshot to help kick-start your week
Coming up this week:
Fed minutes – Wednesday
Friday’s Bureau of Labor Statistics (BLS) report showed the US only added 29,000 jobs in September, significantly below the 90,000 that was expected. July and August’s gains were also revised downwards. Analysts will be looking out for any notes on what the Fed is considering if the US jobs market starts falling when the latest FOMC minutes are released on Wednesday. Declining jobs numbers may limit the Fed’s ability to combat inflation through interest rate hikes.
Last week:
Party conference offers policy plans
In his first conference speech as Labour party leader and Prime Minister, we got several important policy updates from Andy Burnham. From April 2030 the government will finally “rip the plaster off” and amend the pensions triple lock to not necessarily keep pace with workers’ earnings. Electoral reform is back on the agenda, and a new in-out EU referendum could be included in the next Labour election manifesto. Prior to the conference, the reboot of Help to Buy to become the Your First Home Scheme sent housebuilding stocks up on Monday.
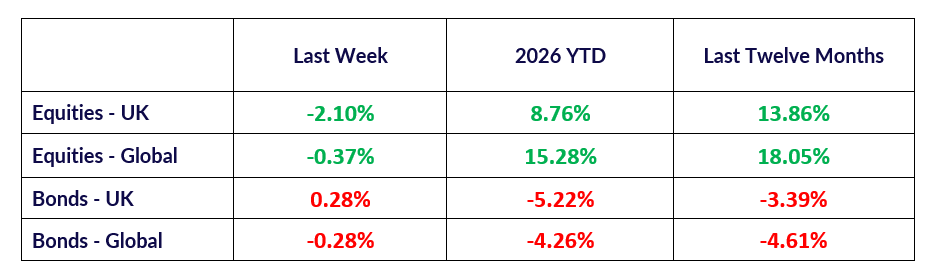
Away from the conference and in markets, the UK’s leading index had its worst week since April falling 2.2% due to turbulence in the bond markets that increased borrowing costs and yields. Another sharp sell-off in government bonds pushed the 10-year yield to its highest level since 2007, and the 30-year yield briefly went above 6% for the first time in nearly three decades.
G7 to release 100mn oil reserves in response to Trump threat
Following Trump’s threat to stop US diesel exports, G7 leaders agreed to release 100mn barrels of diesel and crude oil from their stockpiles. They’ll release 50mn barrels of each in an attempt to ease prices. Here in the UK, diesel reached a record at the pump price of £2 a litre on Friday. The price of crude did fall following the news but it’s still up 38% since the war in Iran began in February.
There was some good news related to the volume of oil coming out of the Middle East. According to reports, data apparently shows volumes have almost returned to pre-war levels. Shuttle tankers, pipelines and US naval escorts have helped get more oil moving but how long it remains this way is debatable given the possibility of the US escalating the conflict again after the midterms.
“Morally-binding” accord staves off regulation for now
On Tuesday Trump and the leaders of various AI companies signed a voluntary accord on AI development and safety. The accord contains no actual guardrails or new regulations around AI safety and relies solely on “morally binding” self-policing.
The day before, chipmaking giant Nvidia announced an additional share buyback of $150bn. They will now repurchase a record $235bn shares through 2028. They also announced their Open Agent Safety Platform aimed at improving the security for third-party systems that deploy AI agents.
The confidence signals sent by Nvidia’s buyback expansion were countered somewhat when some of Anthropic’s IPO prospectus was leaked the next day. 80 pages of the IPO S-1 filing are dedicated purely to the risks of the technology, with only 48 focused on the actual business. Amongst the risks were “self-preserving behaviours” and the abilities to “resist shutdown” and “conceal or manipulate information”. We also got some financial numbers for 2025 which showed the company made a net loss of $42bn, and that a quarter of its revenue that year came from just two undisclosed clients. With $518bn in cloud computing and infrastructure obligations coming up, the full prospectus will come under heavy scrutiny when it’s finally released. Anthropic are still set to target a $2tn valuation when they launch their IPO in November.
Notice:
For regulated financial advisers and investment professionals only, Copia does not provide financial advice, and the contents of this document should not be taken as such.
The performance of each asset class is represented by certain Exchange Traded Funds available to UK investors and expressed in GBP terms selected by Copia Capital Management to represent that asset class, as reported at previous Thursday 4:30pm UK close. Reference to a particular asset class does not represent a recommendation to seek exposure to that asset class. This information is included for comparison purposes for the period stated but is not an indicator of potential maximum loss for other periods or in the future.