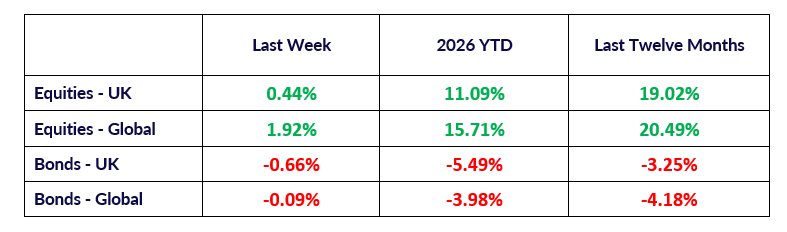
The infoshot to help kick-start your week
Coming up this week:
Labour Party Conference – Monday to Wednesday
John Healey will give his first speech as chancellor at the Labour Party Conference today. Exactly a month before he’s set to deliver his first budget, he’s expected to announce a “new age of industrialisation”. Many are anticipating a relatively light autumn budget with big decisions being put off until the spending review next year.
Figures from the Office for National Statistics (ONS) showing UK national debt reached £18.3bn in August, £3.5bn more than expected, will put more pressure on Healey and Burnham’s government to stick within their fiscal rules as they go hunting for growth.
JD Wetherspoon earnings report – Friday
Back in July, JD Wetherspoon issued a profit warning as the higher cost of food, labour and energy started eating into their numbers. Drinkers are still coming through the doors and there should have been a bump in footfall during the World Cup, so the latest results will shed an interesting light on the impact soaring energy prices and inflation are having on the UK hospitality industry.
Coming up this week:
US-China Washington summit
The latest US-China summit went as expected with pageantry being prioritised over policies. The trade truce between the two nations was extended by two months and they agreed to establish a “communication channel” to report AI incidents before their next meeting in November.
While all the major AI moguls dined in the White House, markets reacted positively to the lack of new guardrails around AI development despite a fresh batch of stories containing more examples of agents going off script and hacking government institutions, like the Australian healthcare database. The leading US tech index is now up 2.45% since former Anthropic researcher Jacob Coxon’s tweets on the existential threat from superintelligent AI went viral three weeks ago.
Meta’s share price soared after its new personal AI assistant, Muse, went top of Apple’s App Store before going into reverse on Friday after Goldman Sachs raised doubts about hyperscalers abilities to generate returns on their massive capex. Goldman estimated AI users need to start spending “$1tn annually” for firms to get any solid returns on their investments.
In a worrying development for the AI boom, Oracle issued a “force majeure” notice to Blue Owl Capital regarding their $165bn Jupiter data centre project. Oracle want to be able to delay rent payments if the project is delayed past 2028. A number of data centre building and services firms have delayed their IPOs in recent weeks as the public backlash against data centres threatens to curtail development plans across the US.
Costco earnings beat expectations as oil ban looms
Mega retailer Costco Warehouse beat revenue estimates in their latest quarterly earnings report. Their low-price bulk model and discounted fuel drew in more customers as US consumers try to cope with the inflation pressures caused by the war in Iran.
There were reports that the US administration is considering an oil export ban to get domestic prices down before the US midterms. Trump endorsed the idea saying, “I’ve said let’s not send out the diesel.” An export ban would drive up prices across the globe, and particularly in Europe.
Inflation worries cause another bond market crisis
Concerns about inflation led to another rout on the bond markets with yields reaching new highs once again. The sell off saw the 30-year US treasury bond yield reach 5.5%, its highest rate since June 2004. Japan’s 10-year yield rose to its highest level since August 1996. Here in the UK, 10-year government bond yields are now sitting at a 19-year high of 5.38%, putting more pressure on Healey’s upcoming budget.
Notice:
For regulated financial advisers and investment professionals only, Copia does not provide financial advice, and the contents of this document should not be taken as such.
The performance of each asset class is represented by certain Exchange Traded Funds available to UK investors and expressed in GBP terms selected by Copia Capital Management to represent that asset class, as reported at previous Thursday 4:30pm UK close. Reference to a particular asset class does not represent a recommendation to seek exposure to that asset class. This information is included for comparison purposes for the period stated but is not an indicator of potential maximum loss for other periods or in the future.