The infoshot to help kick-start your week
Coming up this week:
US-China summit in Washington – Wednesday to Friday
The soon-to-be-expiring trade truce and the global energy crisis might have to take a backseat to AI when Trump and Xi meet this week in Washington.
After a week of nonstop press coverage that has seen the existential threat from superintelligent AI enter the mainstream discourse, investors will be watching out for any agreements that allow for a mutual ‘slowdown’. On Sunday, Treasury Secretary Scott Bessent said a new AI safety notification mechanism has been proposed for the two leaders to consider during the summit. While it looks unlikely either Trump or Xi will be willing to put further guardrails in place, according to leaks this weekend, some senior officials in the Trump administration are frustrated about his refusal to take the subject seriously. It is suggested they may try to convince Trump to push for more oversight and international agreements with China.
Costco earnings report – Thursday
Mega retailer, Costco Wholesale will provide a valuable insight into the health of US consumers when they release their quarterly earnings on Thursday. US drivers have been turning to Costco’s warehouse club as they stock up on fuel at discounted prices instead of heading to the pumps for regular top ups. Costco recently started rationing motor oil and it’ll be interesting to see how supply side pressures impact their expectations for earnings going forward.
Last week:
Tech bounces back from the apocalypse
Across the globe, tech stocks and shares of firms involved in the AI supply chain fell last Monday after the leaders of the US AI frontier labs all called for a slowdown in AI development.
Trump dismissed the calls, calling them a “sick conspiracy “and posted the only “guardrails” AI needs are a “STRONG AND SMART (High IQ) PRESIDENT”. Nvidia CEO, Jensen Huang, also rejected the calls, speaking at the Salesforce Dreamforce conference, “The market forces are already there. We don’t need any new laws. We don’t need new regulations.” The comments from both seemed to reassure investors that no slowdown was imminent, stabilising markets on Tuesday.
Energy crisis deepens
The prices of both brent and crude oil fell by more than 5% last week but there were more worrying signs around global supplies.
Mike Wirth, Chevron’s CEO, said all the mechanisms to help control prices and prevent a supply risk “have been largely played, and we don’t have nearly the buffers in the system that we did when it [the war in Iran] began.” The International Energy Agency (IEA) warned we won’t see supplies return to normal until 2027 and said the “global refining system is stretched to the limit”.
With the US midterm elections just six weeks away, polling by CNN this weekend showed Trump’s current approval rating for gas prices is at minus 80%. TTF natural gas is now up 141% since the war began. The spike in jet fuel, up 85%, has forced several US airlines to start cancelling flights and adjusting schedules around Thanksgiving and Christmas.
As widely expected, the Federal Reserve voted to increase interest rates for the first time in three years to help combat inflation. Markets reacted remarkably well to the news, with many aware that a higher two or three basis point rate hike might actually be required to start tackling the inflation problem.
Canada offered chance to become EU associate member
European Commission President, Ursula von der Leyen has proposed that Canada should become the EU’s first “associate member”. Canadian President Mark Carney welcomed the proposal on Thursday and listed AI, critical minerals, defence, energy security and the space sector as the key areas Canada and the EU could cooperate more closely on. Trump labelled the proposal a “hostile act” and said he will put “very serious tariffs or stop trading with Europe, on many things” if membership status is granted.
Notice:
For regulated financial advisers and investment professionals only, Copia does not provide financial advice, and the contents of this document should not be taken as such.
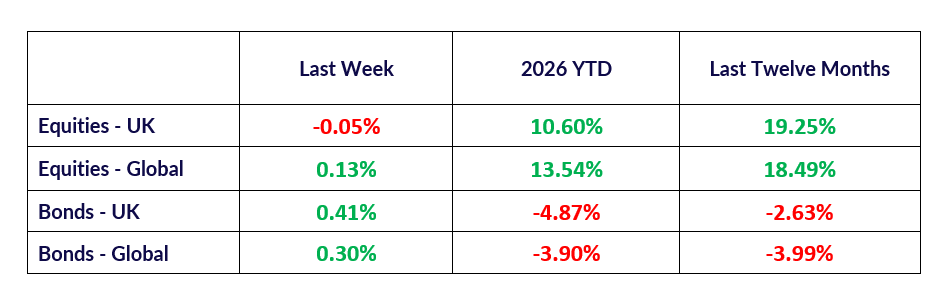
The performance of each asset class is represented by certain Exchange Traded Funds available to UK investors and expressed in GBP terms selected by Copia Capital Management to represent that asset class, as reported at previous Thursday 4:30pm UK close. Reference to a particular asset class does not represent a recommendation to seek exposure to that asset class. This information is included for comparison purposes for the period stated but is not an indicator of potential maximum loss for other periods or in the future.